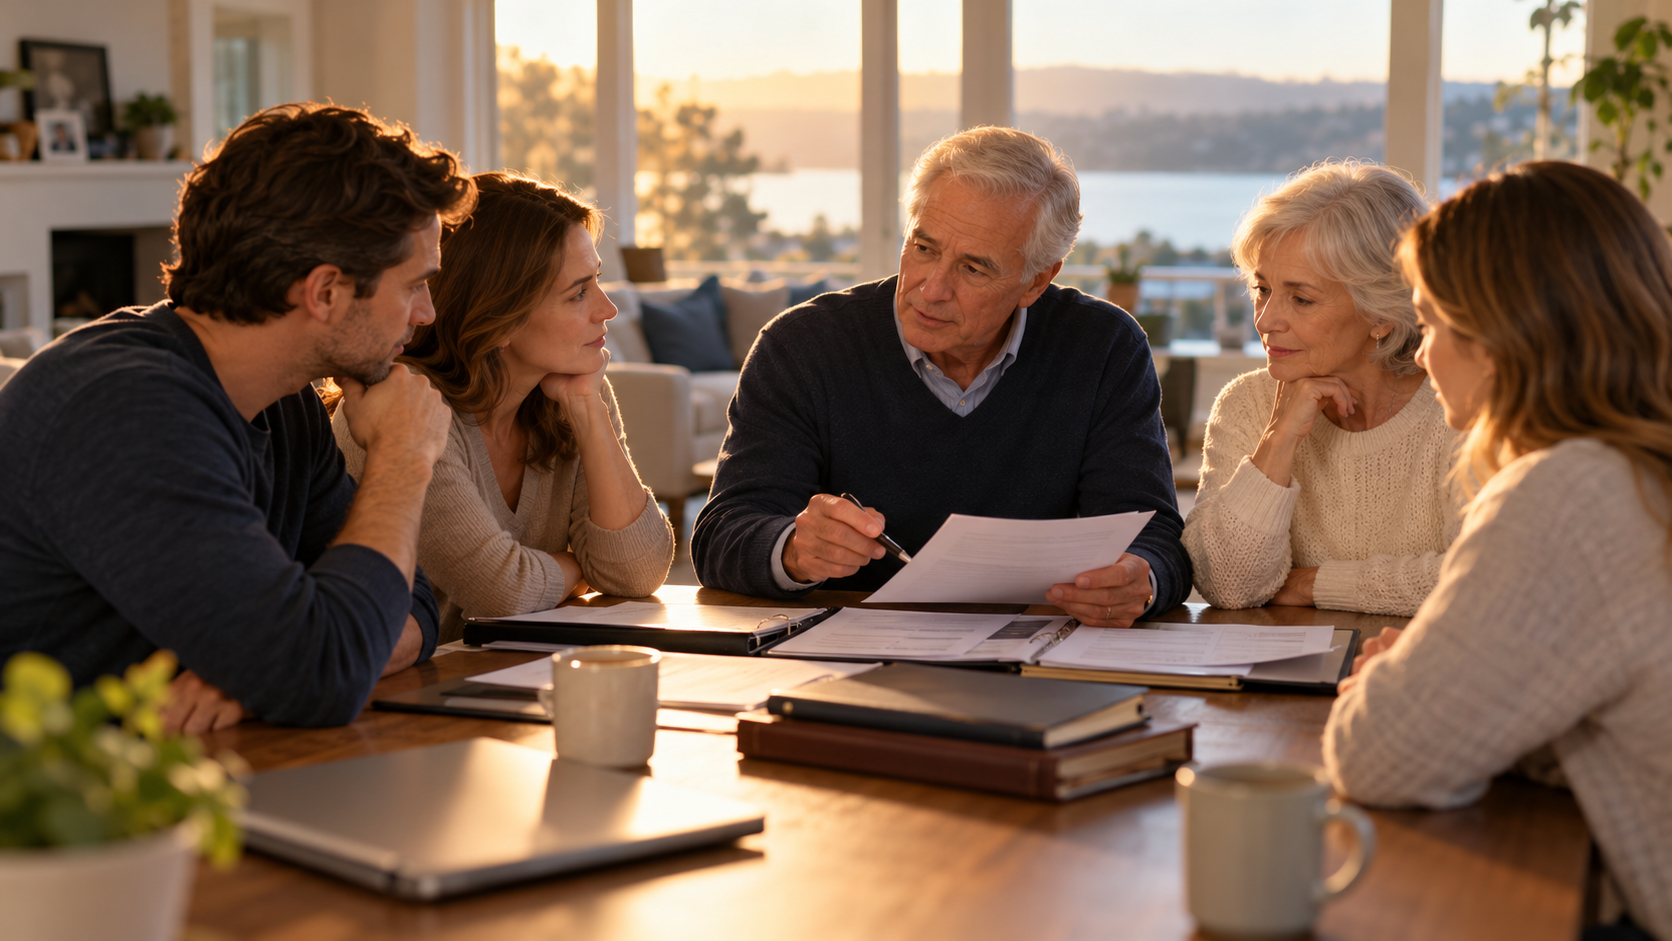
Most families avoid talking about death until they have no choice. But end of life planning helps you make important decisions before your loved ones are left guessing. Does your spouse know where your financial documents are? Do your children understand your healthcare wishes? Having these conversations now can help your family avoid confusion, difficult decisions, and disagreements during an already emotional time.
Why Is End of Life Planning More Than Having a Will?
A will explains how you want certain assets distributed after your death. But it doesn't necessarily tell your family what medical care you prefer, who should manage your finances if you become incapacitated, or how you hope your wealth will benefit future generations. Effective end of life planning addresses these questions before an emergency makes them urgent.
The National Institute on Aging recommends organizing important documents, discussing healthcare preferences, and reviewing plans regularly. Your estate plan provides legal instructions, while conversations help your family understand the reasoning behind your decisions. Together, they can reduce uncertainty and give your loved ones a clearer sense of direction.
Read: 12 Things You Need to Know to Build a Strong Estate Plan
What Healthcare Decisions Should Your Family Know About?
Imagine your family sitting in a hospital waiting room, trying to agree on medical treatment when you can no longer speak for yourself. One person believes you would want every possible intervention. Another remembers you expressing different wishes. Without clear instructions, even a close family can struggle to make decisions. Advance care planning gives you an opportunity to explain your preferences while you can still communicate them.
Start by discussing life sustaining medical treatment, comfort care, and who should speak on your behalf. A living will can document treatment preferences, while a healthcare power of attorney names someone to make medical decisions when you cannot. A HIPAA authorization can also help designated individuals access relevant medical information. Requirements vary by state, so review these documents with your healthcare provider or attorney.
Which Estate Planning Documents Should You Prepare?
An estate planning checklist helps you organize the documents your family may need to manage your affairs. Having these documents in place provides instructions for handling your finances, healthcare decisions, and assets if you become unable to manage them yourself.
Estate Planning Checklist
Tap the box next to each item to check it off as you review it.
| Done | Document or item | What it does |
|---|---|---|
| Core documents | ||
| Outlines how your assets should be distributed, names an executor, and can identify your preferred guardian for minor children. | ||
| Provides instructions for managing and distributing assets held in the trust. Remember that a trust generally needs to be funded by transferring the appropriate assets into it. | ||
| Healthcare and incapacity | ||
| Appoints someone to make healthcare decisions if you cannot communicate your wishes. | ||
| Documents your preferences for medical treatments and end of life care. | ||
| Authorizes a trusted person to manage specified financial matters on your behalf, including during incapacity. | ||
| Allows designated individuals to access certain medical information, subject to applicable privacy rules. | ||
| Assets and accounts | ||
| Lists properties, bank accounts, investments, outstanding debts, and other financial obligations. | ||
| Identifies who receives assets from retirement accounts, life insurance policies, and applicable financial accounts. Valid beneficiary designations generally take precedence over instructions in your will. | ||
| Reviews the student beneficiary and identifies a successor account owner who can manage the account if the current owner dies, where the plan permits. | ||
| Reviews joint ownership arrangements and transfer on death (TOD) or payable on death (POD) designations that may transfer assets outside your will. | ||
Once you've completed your estate planning checklist, organize your documents in a secure location and tell trusted family members where to find them. Review your plan after major life changes, such as marriage, divorce, or the birth of a child. An estate planning attorney can help determine which documents are appropriate for your circumstances.
Does Your Family Understand Your Financial Situation?
Your family may know that you own a home and have retirement savings, but do they know which institutions hold your accounts? What about outstanding debts, insurance policies, investment properties, or business interests? Financial information often sits across multiple accounts, advisors, and filing systems. When nobody has a complete picture, settling an estate can become harder to manage.
Create a financial inventory that identifies your assets, liabilities, insurance coverage, and key professional contacts. Include bank accounts, retirement plans, investment accounts, mortgages, tax records, and any 529 education savings plans. You don't need to share every account balance during a family conversation. Start by explaining what exists, who manages it, and where authorized individuals can access the information when necessary.
Read: Will, Trust, or Both? Here's How to Decide
Have You Explained the Purpose Behind Your Wealth?
Money can become a sensitive subject when family members don't understand the intentions behind an inheritance. Why does one beneficiary receive assets through a trust while another receives them outright? Why are certain funds reserved for education or charitable giving? Without context, family members may interpret these decisions in ways you never intended.
Discuss what you want your wealth to accomplish. Perhaps your priority is financial independence for your children, educational opportunities for grandchildren, or support for causes that matter to your family. Explain your thinking without turning the conversation into a list of expectations. A family discussion can help loved ones understand the purpose behind your estate planning decisions while giving you an opportunity to hear their perspectives.
Who Will Make Decisions When You No Longer Can?
Naming someone in your estate planning documents is only the first step. You also need to prepare them for their responsibilities. Here are the key decision makers your family should know:
Executor: Locates assets, addresses debts, coordinates with professionals, and manages estate administration.
Trustee: Manages and distributes assets held in a trust according to its terms.
Durable Financial Power of Attorney: Authorizes someone to handle specified financial decisions on your behalf during your lifetime.
Healthcare Power of Attorney: Authorizes someone to make medical decisions if you're unable to communicate your wishes.
Before these individuals need to act, discuss their roles and confirm they're willing to serve. Introduce them to your estate planning attorney, financial advisor, CPA, and insurance professional. Remember that powers of attorney generally end at death. At that point, your executor or another legally authorized representative becomes responsible for administering your estate.
What Happens to Your Digital Accounts and Personal Wishes?
Your financial life doesn't end with bank statements and property deeds. Email accounts, online subscriptions, digital photographs, cloud storage, reward points, and other digital assets may require attention. If nobody knows these accounts exist, important records and personal memories could become difficult to retrieve. Some services also have specific rules governing account access after death.
Create a secure digital asset inventory and document your preferences for managing those accounts. Avoid putting passwords directly in your will, as wills may become public during probate. Instead, consider secure password management tools and legacy contact features offered by services such as Apple and Google. You should also discuss funeral arrangements, burial or cremation preferences, organ donation, and meaningful family traditions.
Could Your Estate Plan Create Unexpected Tax Consequences?
Estate planning involves more than deciding who receives your property. In 2026, the federal estate and gift tax basic exclusion is $15 million per individual, with married couples potentially able to preserve up to $30 million through applicable planning and portability rules. However, some states impose their own estate or inheritance taxes with different thresholds. Even if your estate falls below the federal exemption, your family could still face state tax obligations.
Other financial considerations include inherited retirement accounts, beneficiary designations, charitable giving, and lifetime gifts. For example, many non spouse beneficiaries must withdraw inherited IRA funds within 10 years, although exceptions apply. Working with your estate planning attorney, CPA, and financial advisor can help you understand how these rules affect your family and coordinate your financial decisions.
What Do You Want Your Family to Remember About You?
Some of the most meaningful end of life conversations have little to do with money. What experiences shaped your values? What lessons would you like your children or grandchildren to remember? What family traditions should continue? These questions give you an opportunity to share stories and perspectives that legal documents cannot capture.
Consider writing a legacy letter or recording conversations about your life, relationships, and hopes for future generations. You might also involve family members in charitable activities or traditions while you're still able to participate. Your legacy doesn't have to wait until your estate is distributed. You can begin sharing it through the relationships and experiences you create today.
How a Virtual Family Office Can Help
End of life planning often involves several professionals working on different pieces of your financial life. Your attorney prepares legal documents, your CPA evaluates tax considerations, and your financial advisor manages investment strategies. But decisions made separately may not always reflect the same family priorities. A Virtual Family Office (VFO) approach brings these conversations together, helping you see how your estate, financial, and tax plans connect.
Through a coordinated team of advisors, a VFO can help organize financial information, identify planning gaps, facilitate family discussions, and support the implementation of your decisions. This approach can be particularly helpful when your family has multiple properties, business interests, complex investments, or multigenerational goals. The objective is to give your loved ones a clearer plan and a better understanding of the responsibilities ahead.
Read: What Is Virtual Family Office and Why More Families Are Moving to It
Bottom Line
You can't prepare your family for every situation, but you can give them the information they need to make difficult decisions with greater confidence. Start with one conversation. Discuss your healthcare wishes, organize your estate planning documents, explain your financial priorities, and make sure the people you've chosen understand their responsibilities.
At ONE Advisory Partners, we believe thoughtful planning should connect your finances with the people and priorities that matter most. If your estate plan involves multiple advisors, complex assets, or important family decisions, contact our team to learn how a coordinated approach can help you prepare for the future.
Frequently Asked Questions About End of Life Planning
What is end of life planning?
End of life planning involves preparing legal, medical, financial, and personal instructions for situations involving incapacity or death. It includes documenting your wishes, selecting decision makers, organizing records, and communicating with loved ones.
When should you start end of life planning?
End of life planning should begin at age 18, even if you have limited assets. Healthcare directives and powers of attorney can help clarify who may make decisions if you're unable to act for yourself. Review your plan after major life events, including marriage, divorce, childbirth, or significant financial changes.
What are the most important end of life planning documents?
Common documents include a will, living will, healthcare power of attorney, durable financial power of attorney, and potentially a trust. Your circumstances and state laws determine which documents you need.
How do you start an end of life conversation with your parents?
Choose a quiet moment and explain that you want to understand their preferences, not control their decisions. Begin with questions about healthcare wishes, important documents, and who they trust to manage their affairs.
What happens if someone dies without an estate plan?
State laws generally determine how assets subject to intestacy are distributed. Family members may also face additional legal procedures and uncertainty about responsibilities. Beneficiary designations and other ownership arrangements may affect which assets pass through the estate.
References
Internal Revenue Service. (n.d.). Estate and gift tax FAQs. Retrieved from https://www.irs.gov/newsroom/estate-and-gift-tax-faqs www.irs.gov
Internal Revenue Service. (n.d.). Required minimum distributions for IRA beneficiaries. Retrieved from https://www.irs.gov/retirement-plans/required-minimum-distributions-for-ira-beneficiaries www.irs.gov
National Institute on Aging. (n.d.). Getting your affairs in order checklist: Documents to prepare for the future. Retrieved from https://www.nia.nih.gov/health/advance-care-planning/getting-your-affairs-order-checklist-documents-prepare-future www.nia.nih.gov
National Institute on Aging. (n.d.). Advance care planning: Advance directives for health care. Retrieved from https://www.nia.nih.gov/health/advance-care-planning/advance-care-planning-advance-directives-health-care www.nia.nih.gov